Blog · All posts · The Neighbourhood
How Much House Can You Afford in Port Perry in 2026?
2026-10-16 · Buying · By Keith Williams & Lisa C. Follows
Key takeaways
- Scugog’s average home price was about $1,000,000 in September 2026, up 22.4 percent from August but down 7.9 percent year over year, with detached homes averaging $1.02 million, per TRREB figures published by DurhamRegion.com.
- The minimum down payment in Canada is 5 percent on the first $500,000 of the price and 10 percent on the portion above it, up to $1.5 million. On a $1,000,000 home that is $75,000; 20 percent, or $200,000, avoids mortgage insurance.
- Lenders qualify you at the stress test rate: the greater of your contract rate plus 2 percentage points, or 5.25 percent. With 5-year fixed rates around 4.4 to 4.6 percent in October 2026, most Port Perry buyers are qualified near 6.4 to 6.6 percent.
- A $1,000,000 home with 20 percent down carries a mortgage of $800,000 and a payment of roughly $4,450 a month at 4.5 percent over 25 years, plus about $1,110 a month in Scugog property taxes, before heat and utilities.
- Where you buy changes the number more than the town average does: walkable in-town streets, lakefront communities like Highland Beach and Cedar Shores, and hamlets such as Blackstock and Prince Albert each carry their own price per square foot.
How much house can you afford in Port Perry in 2026? In plain numbers: with 20 percent down on a $1,000,000 home, close to Scugog’s September 2026 average, your mortgage is $800,000 and your payment is roughly $4,450 a month at a 4.5 percent fixed rate over 25 years, before about $1,110 a month in property taxes. Under the minimum down payment rules, that same home needs $75,000 down. This guide walks the full worked math, the rules that decide what you qualify for, and what each budget actually buys on the streets of Port Perry and Scugog.
We are Keith Williams and Lisa C. Follows, brokers with Willows Realty Group, and we help buyers in Port Perry and across Durham Region every week. This guide answers the affordability questions families ask us most: what price should I look at, how much do I need for the down payment, what will the monthly payment really be, and which streets fit my budget?
How much does a home in Port Perry cost right now?
Start with the data, then treat the average as a range, not a price tag. TRREB reports Scugog as one market area, and the most recent verified figure puts the average home price at about $1,000,000 in September 2026, up 22.4 percent from August but down 7.9 percent from a year earlier, with detached homes, the most common type in town, averaging $1.02 million, per the monthly TRREB figures published by DurhamRegion.com. Only 23 homes sold that month, so the average swings with a handful of lakefront sales.
The monthly band tells the fuller story. Scugog averaged $940,675 in January 2026, $865,895 in April, $944,997 in May and $819,217 in August before the September jump, with third-party trackers such as Zolo putting the September figure near $942,000 on a median of 37 days on market. Our fall 2026 Scugog market update tracks that band month by month, and the 2026 Port Perry market guide keeps the averages and the neighbourhood breakdown in one place.
The down payment rules that set your floor
Canada’s minimum down payment rule is simple: 5 percent on the first $500,000 of the price, and 10 percent on the portion above that, up to $1.5 million, per the Financial Consumer Agency of Canada. On the September average of $1,000,000, the minimum is $25,000 plus $50,000, so $75,000. Put down 20 percent, or $200,000, and you skip mortgage insurance entirely, which in this price range is a meaningful monthly saving.
A related change matters for first-time buyers: since December 2024, insured mortgages on homes up to $1.5 million can stretch to a 30-year amortization for first-time buyers and for buyers of newly built homes. A longer amortization lowers the monthly payment, though it adds interest over the life of the loan, so it is worth weighing carefully. For the full step-by-step on deposits, closing costs and the first-home process, our first-time buyer’s guide to Port Perry goes deeper.
What does the monthly payment look like on a Scugog home?
Here is the math buyers actually run. These are illustrative examples with stated assumptions; your lender’s figure will differ:
On $1,000,000 with 20 percent down: mortgage of $800,000. At a 4.5 percent 5-year fixed rate over 25 years, the principal and interest payment is about $4,450 a month. Scugog’s combined residential tax rate, roughly 1.33 percent, adds about $1,110 a month on that assessment, and heat and hydro add a few hundred more. The all-in number is close to $5,900 a month.
On $800,000 with 20 percent down: mortgage of $640,000, a payment of about $3,550 a month at the same rate and term, and roughly $890 a month in property taxes, for an all-in figure near $4,700.
On $700,000 with a smaller down payment: under the 5 and 10 percent rules, the minimum down payment is $45,000, with mortgage insurance added to the loan. A $655,000 insured mortgage at 4.5 percent over 30 years (the option open to first-time buyers) lands near $3,300 a month, before taxes of about $780 a month.
Hold the important caveat: these are before other debts, condo fees if they apply, and the insurance premium folded into the mortgage. Your lender’s calculator is the real one, and a pre-approval letter turns these scenarios into your number.
The stress test decides what you actually qualify for
Qualifying is not at your contract rate, it is at the stress test rate: the greater of your contract rate plus 2 percentage points, or the 5.25 percent floor set by OSFI, per the Office of the Superintendent of Financial Institutions. With the Bank of Canada’s policy rate at 2.25 percent and discounted 5-year fixed rates around 4.4 to 4.6 percent this fall, most Port Perry buyers are qualified at roughly 6.4 to 6.6 percent, even when their actual payment is lower.
Run that on the $800,000 mortgage: at the qualifying rate it tests closer to $5,350 a month, and once property taxes and heating join in, lenders look for a gross household income on the order of $250,000 before other debts. That is often the biggest surprise for buyers this year: the monthly payment looks manageable, but the qualifying bar is higher. Get a pre-approval before you shop, so the budget you compare homes against is one a lender has already agreed to.
What does your budget actually buy on the ground?
Port Perry is several micro-markets, and the same budget buys very different homes on different streets. Our guide to the best family neighbourhoods in Port Perry lays the street-by-street map out in full; here is the short version.
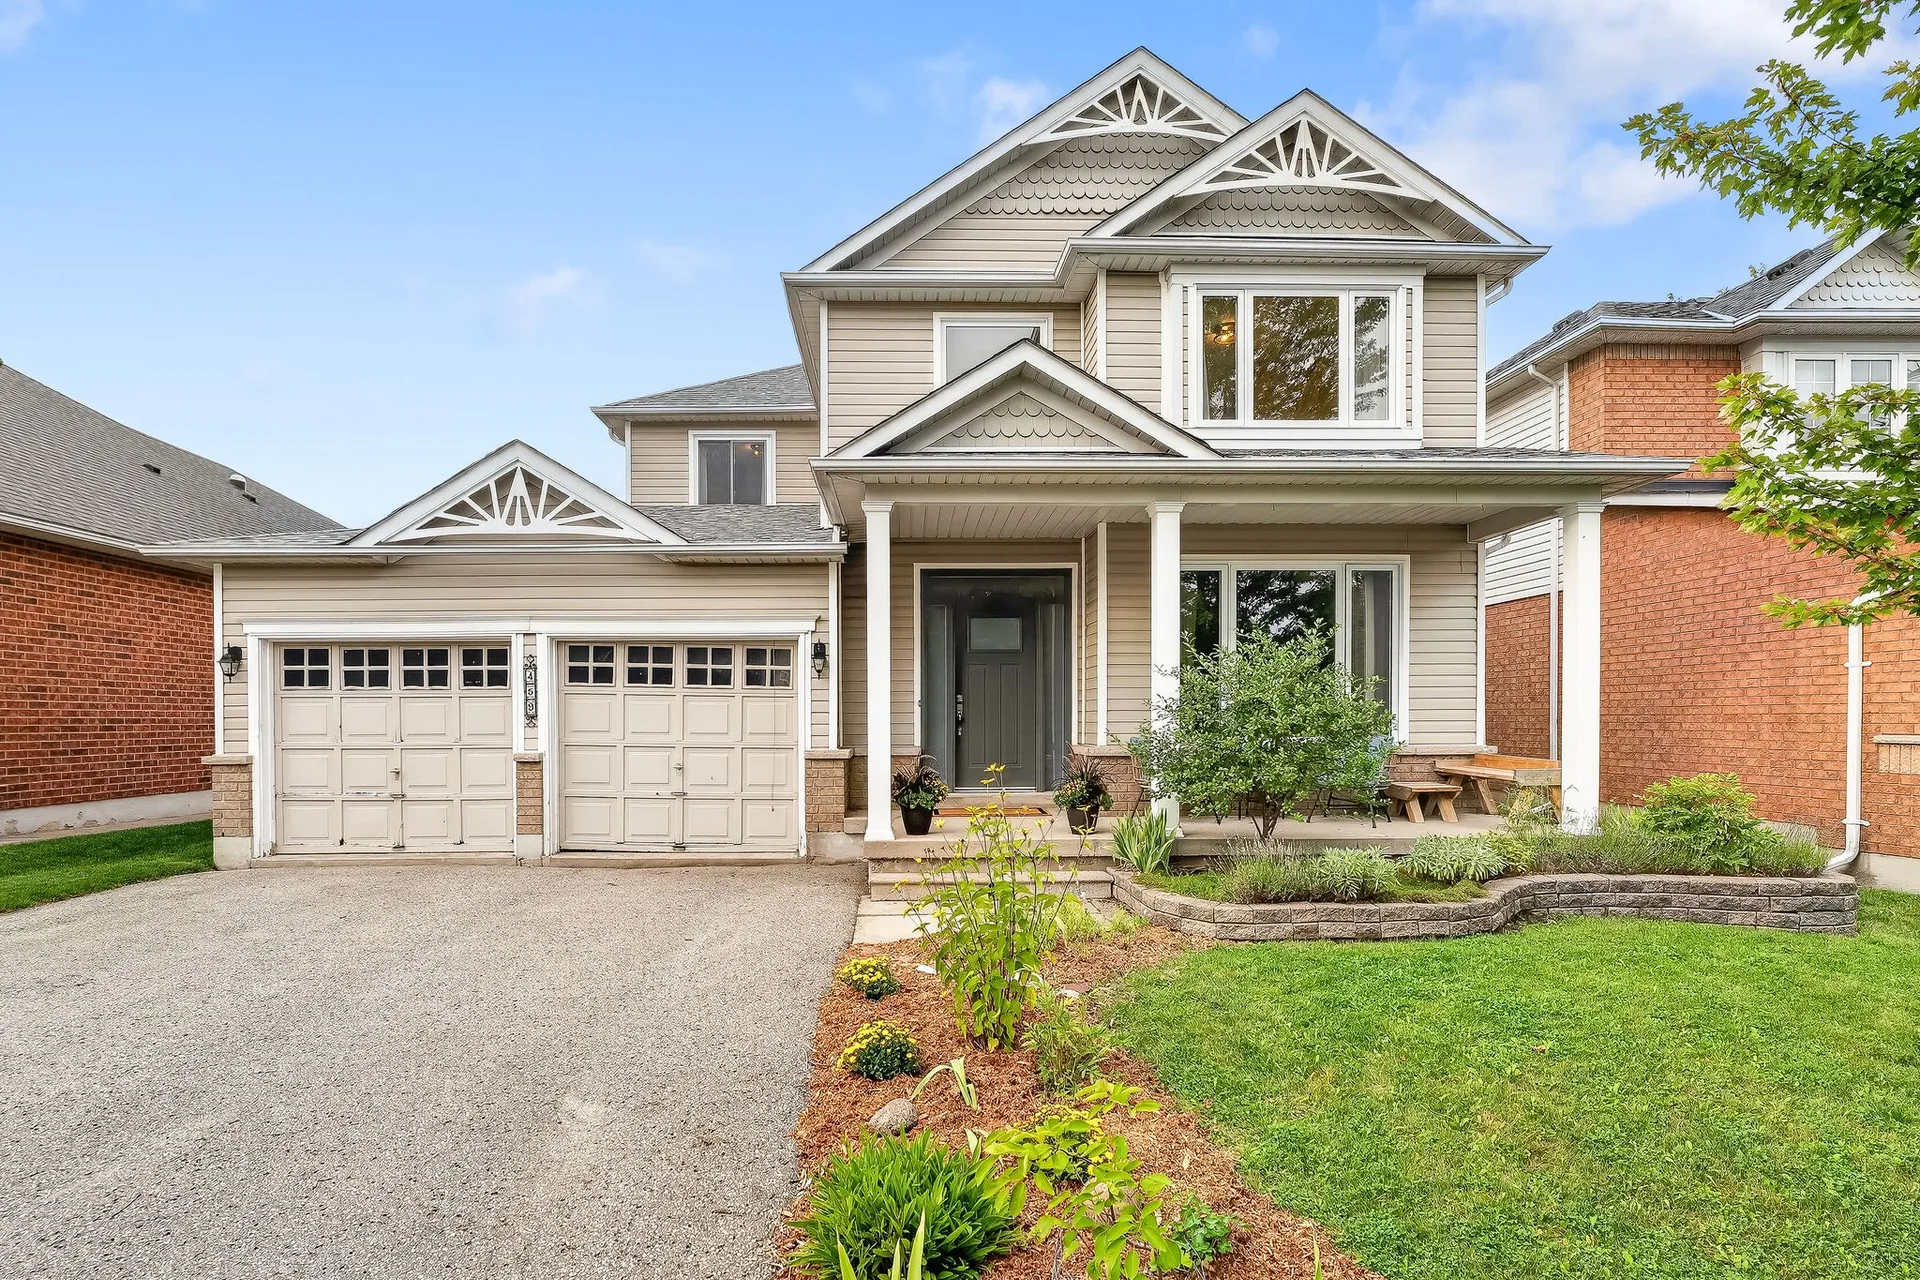
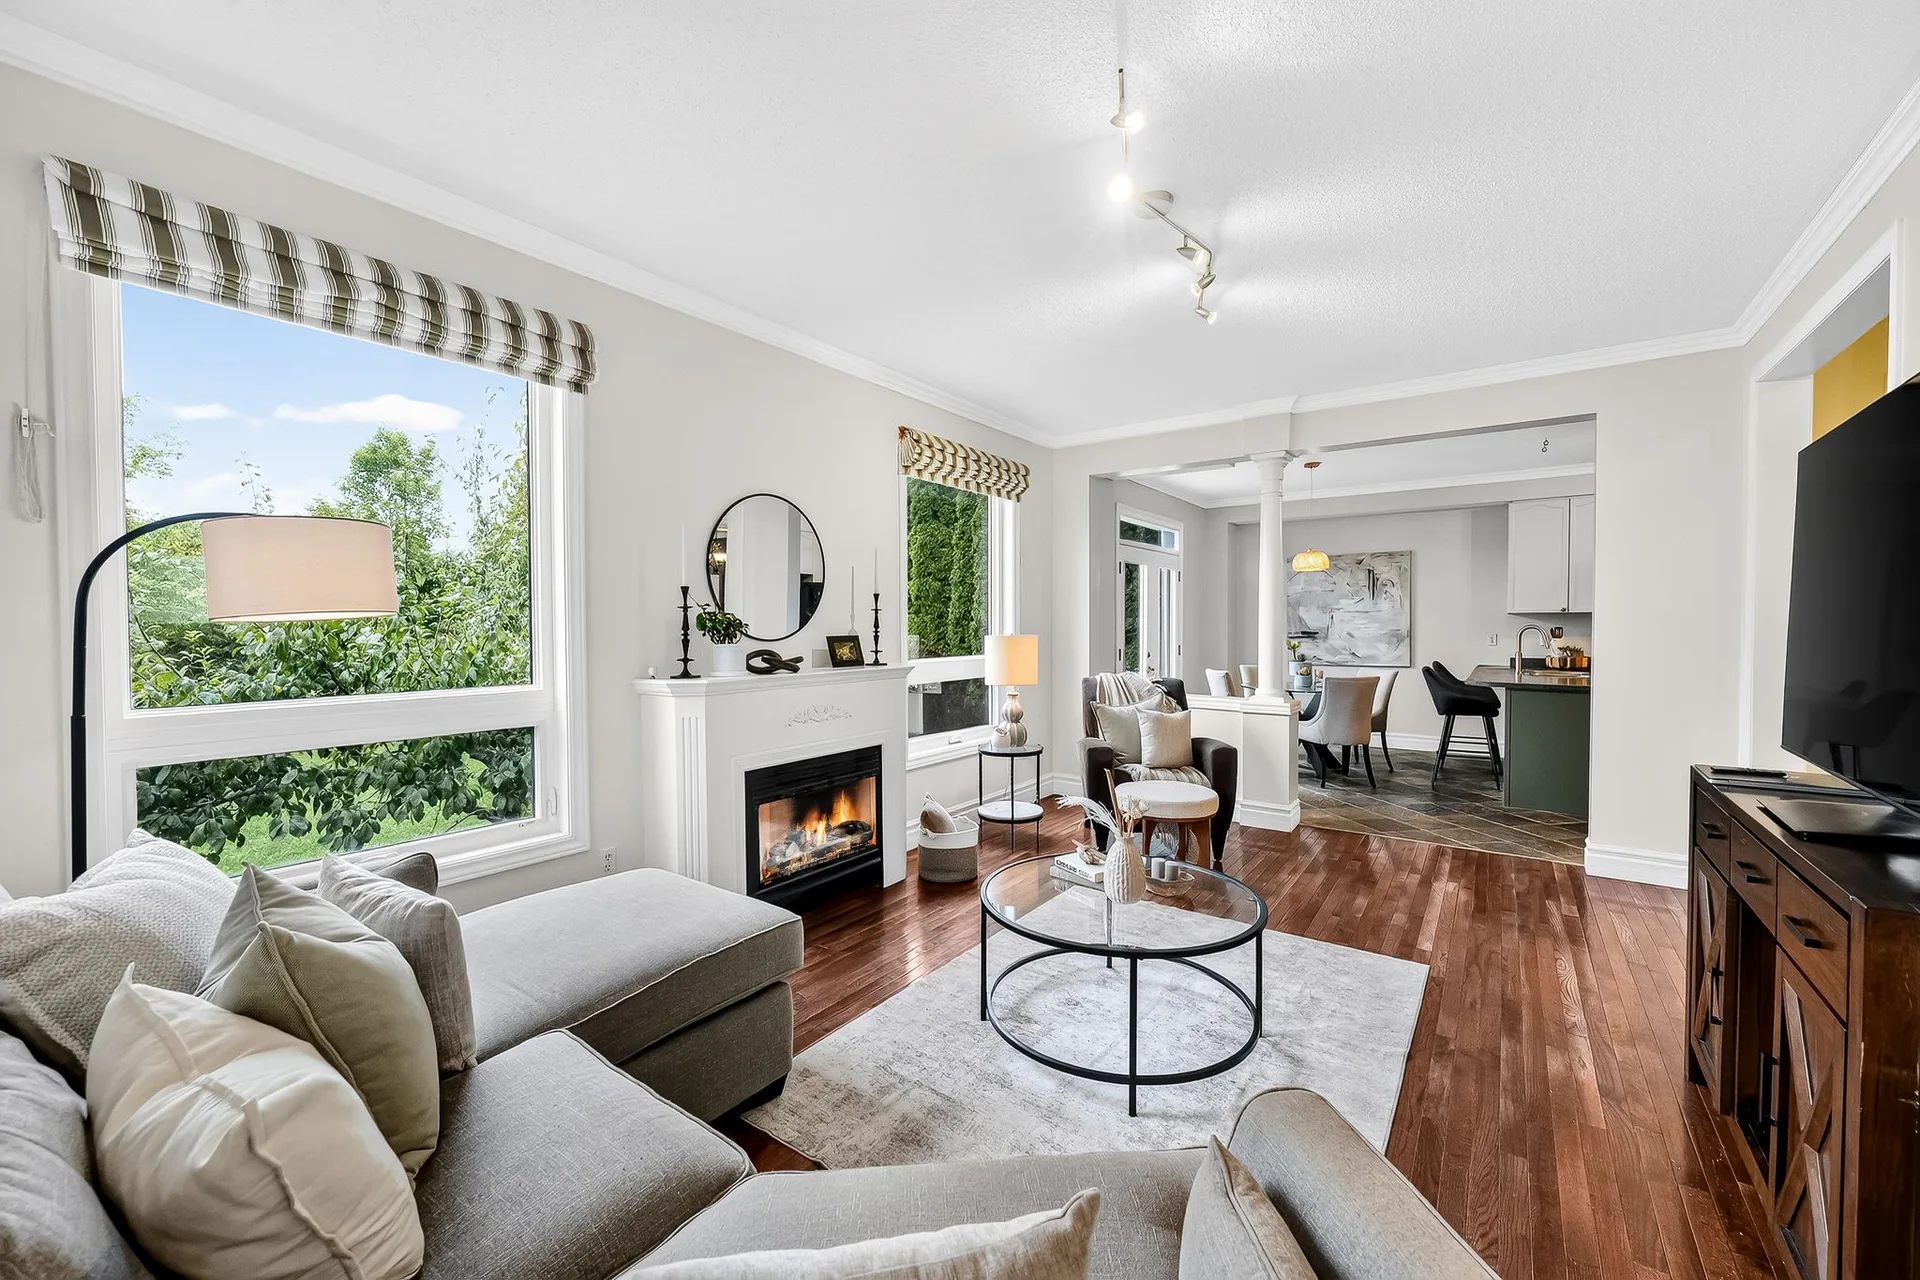
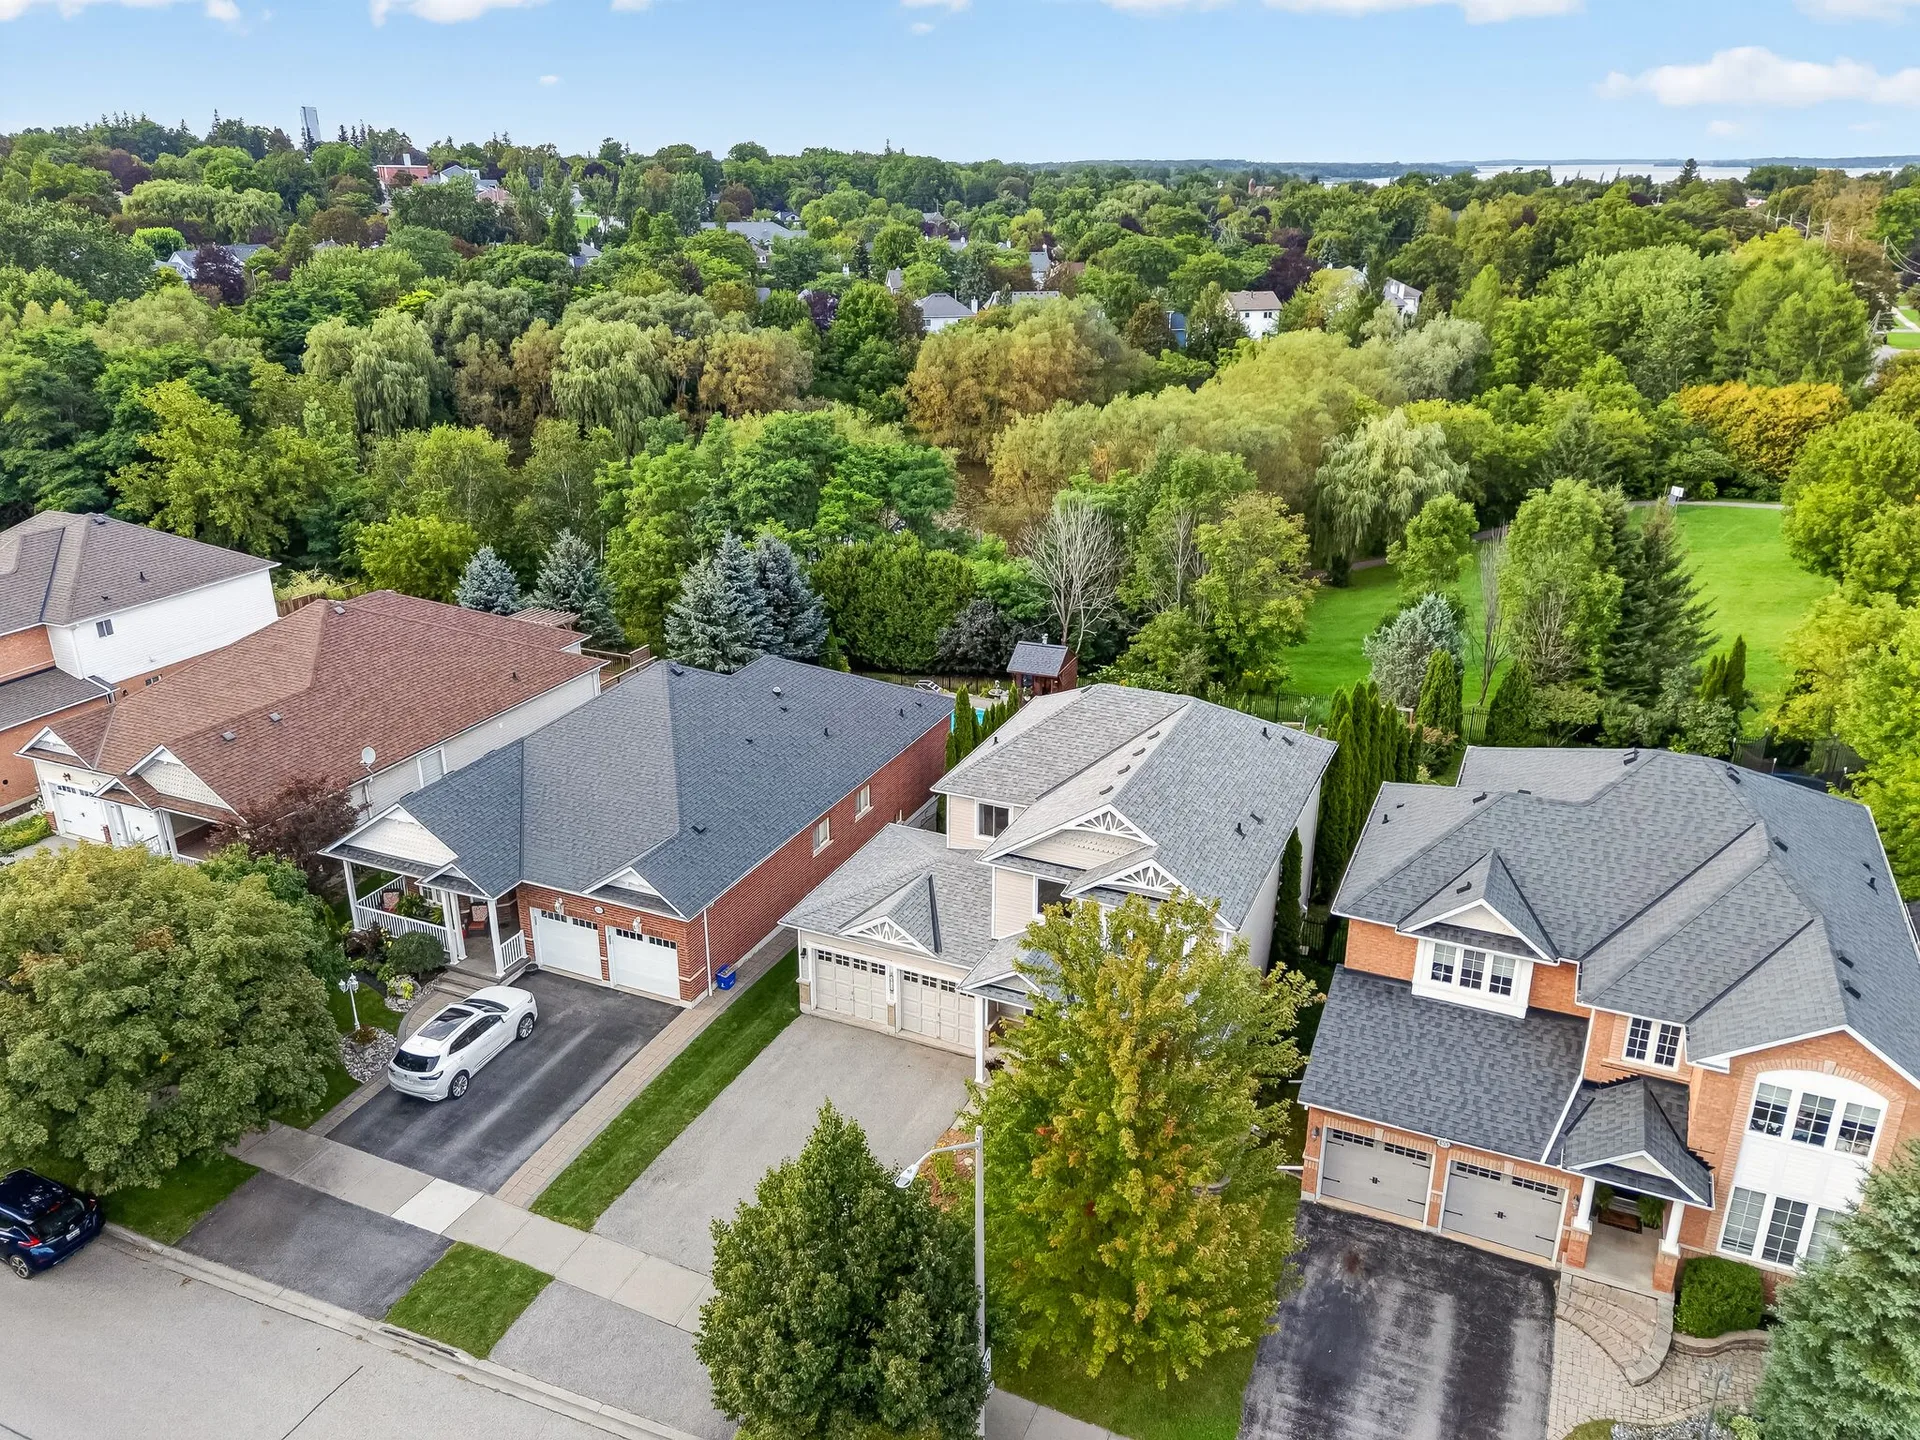
The walkable in-town streets, the mid-century and newer streets around Victoria, Bigelow and Ash, and the heritage core near Queen, Water and Perry, are where families usually start. The school run to R.H. Cornish Public School and Port Perry High School is short, and Queen Street, the library and the Lake Scugog waterfront are a 10 to 20 minute walk. A home like 459 Victoria, with its 2,344 square feet above grade, four bedrooms, fenced garden and green space behind, shows the upper end of that family range, and the Port Perry neighbourhood guide maps what sits in between.
Lakefront communities such as Highland Beach, Cedar Shores and Gerrow’s Beach carry a real premium for water access, often $200,000 or more above comparable in-town homes, so a budget that buys a large family home on Victoria Street may buy a smaller cottage-style home at the water. The rural hamlets around the township, places like Blackstock, Prince Albert and Caesarea, stretch a budget the other way, with more land per dollar and a different commute.
The practical rule: shortlist the street, then compare recent sales on that street, not the township average. That is the only number that tells you what your budget buys.
How to get your real number before you book showings
Turn the averages into your number in one weekend. Start with a pre-approval from a lender or mortgage broker, so you know the price ceiling, the rate you are actually offered and the qualifying income your lender looks for. Add the closing costs: Ontario land transfer tax and legal fees run roughly 1.5 to 4 percent of the price on top of the down payment, with a rebate available to eligible first-time buyers.
Then check the three things that are address-specific before you fall for a listing: the school catchment for the exact street, the walk time to Queen Street or the lake, and the commute once during rush hour. A local team also pulls the recent sales on that street, so you negotiate from evidence rather than averages. That is what we do for every buyer who works with us, starting with a quick conversation.
Affordability in Port Perry, asked plainly
How much house can I afford in Port Perry with a $100,000 down payment?
$100,000 is 20 percent of $500,000, so it buys a $500,000 home with no mortgage insurance, and under the 5 and 10 percent rules it is well above the minimum down payment on a home closer to $900,000. The deciding question is the monthly payment at the stress test rate, not the down payment alone, so work from a pre-approval.
What is the minimum down payment for a house in Port Perry?
Five percent of the first $500,000 plus 10 percent of the portion above it, up to $1.5 million. On Scugog’s September 2026 average of about $1,000,000, the minimum down payment is $75,000. Put down 20 percent and you avoid mortgage insurance.
Do I need CMHC mortgage insurance to buy in Port Perry?
Yes, if your down payment is below 20 percent. The insurance premium is added to your mortgage, so it increases the loan and the monthly payment. A 20 percent down payment avoids it entirely.
What income do I need to buy the average Port Perry home?
On a $1,000,000 home with 20 percent down, qualifying at the stress test rate with property taxes and heating points to a gross household income on the order of $250,000 before other debts. The figure is lender-specific and drops if you carry less mortgage or other debts are minimal.
Can I still get a 30-year mortgage in 2026?
Yes, with an insured mortgage (less than 20 percent down) on a home priced up to $1.5 million: first-time buyers can use a 30-year amortization on any home, and any buyer can use it on a newly built home. It lowers the monthly payment but adds interest over the life of the loan.
Written by your local team
Keith Williams & Lisa C. Follows are licensed Brokers and co-founders of Willows Realty Group, and the local experts and curators of this information. They help buyers in Port Perry and across Durham Region every day, and each week’s guide is built from the questions families actually ask when they start looking. More about the team is on the About page.
Call today to talk about your next move!
Call Lisa or Keith at 905-985-9898.